|
Chuan Holdings is a Singapore contractor that is not well-known in the local investment community likely because it has been listed in Hong Kong since 2016 (IPO price: HK$0.88). |
| Reasons for outperformance |
The biggest surprise was Chuan's core earthworks business.
Earthworks revenue jumped 153% to S$116.8 million, while gross margin expanded from 20.4% to an exceptional 27.0%.
This came despite the diesel-price shock that investors had earlier feared would squeeze profitability.
Chuan attributed the good result to high utilisation of its own machinery, disciplined management of haulage distances and disposal costs, and supply agreements locked in before the Middle East conflict escalated.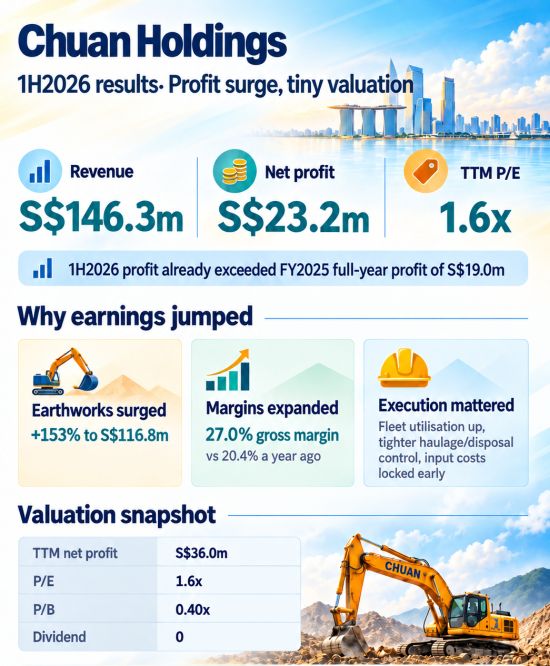 Chuan's trailing 12-month profit = FY2025 + 1H2026 - 1H2025 = 18.96 + 23.189 - 6.166 = S$35.983m
| Reclaims: similar business, different outcome |
SGX-listed Reclaims Global is one of Chuan's closest listed peer. Both are heavily involved in excavation, earthmoving, haulage and heavy machinery.
But Reclaims is more diversified into logistics/leasing and recycling, whereas Chuan is more concentrated in larger earthworks and infrastructure packages.
Reclaims also posted respectable latest-half results: 1HFY27 (ended July 2026) revenue rose 52.9% to S$33.3 million, while net profit increased 53.1% to S$3.8 million.
Excavation revenue rose 47% to S$24.1 million, but recurring EBITDA fell from S$4.0 million to S$2.25 million. In contrast, logistics/leasing EBITDA more than tripled to S$3.13 million, while recycling returned to profit.
Diesel costs nearly doubled to S$1.12 million. Reclaims responded by bidding more selectively and factoring higher diesel costs into new contracts; its generally shorter-duration projects also allow faster repricing.
|
Metric |
Reclaims Global |
Chuan |
|
Share price |
S$0.21 |
HK$0.27 |
|
Market cap |
S$62.7 m |
HK$363 m (~S$58.8 m) |
|
Net profit (TTM) |
S$8.17 m |
S$35.98 m |
|
P/E (TTM) |
7.7x |
1.6x |
|
Price/Book |
1.33x |
0.40x |
|
Dividend/share (TTM) |
1.25 S cents |
0 |
| Valuation gap |
At around HK$0.27, Chuan trades at 1.6x PE and 0.4x book value following the latest results.
Using Reclaims' S$0.215 share price and incorporating its newly reported 1H earnings, its trailing P/E is at 7.8x, with P/B around 1.35x.
The two companies now have remarkably similar market capitalisations — roughly S$60-65 million — despite Chuan producing more than six times Reclaims' latest half-year profit.
The Chuan discount is equally obvious against other Singapore construction names.
| Why so cheap? |
There are reasons for the discount. Chuan is listed in Hong Kong, where a small Singapore contractor attracts less investor attention.
It pays no dividend, while Reclaims offers dividends and has executed share buybacks. Chuan also continues funding the problematic Maxwell House redevelopment.
Management expects 2H operating conditions to remain demanding, while some protection from previously locked-in input prices could disappear.
Still, Chuan's latest results change the argument. It is no longer merely a cheap contractor riding Singapore's construction upcycle.
It has demonstrated accelerating revenue, expanding margins, strong cash generation and surprising resilience to fuel inflation.
If comparable Singapore contractors command 5–13x earnings, how long can Chuan remain below 2x?
Kwan Yong Holdings is another Singapore contractor listed on HKEX that has delivered much stronger results than expected -- and is relatively undervalued. In a profit alert, with final FY2026 results due on 24 Sept, it said it expected net profit attributable to shareholders of about S$19.8 million for the year ended June 2026, up 55% from S$12.8 million a year earlier. The number is particularly impressive because Kwan Yong reported only S$6.9 million of profit in 1HFY2026. This implies 2H profit of roughly S$12.9 million. More importantly, the improvement does not appear to be driven by a one-off gain for the contractor whose contracts have largely been from the public sector, including nursing homes, HDB flats and educational institutions. |
 → See previous article:CHUAN HOLDINGS: At 3.1x P/E, Isn't This Company A Value Play in S'pore Construction Boom?


