|
Yangzijiang Financial has finally begun doing something that shareholders have been asking about for some time: buying back its own deeply discounted shares.
The latest purchase, on 25 Sept, was another 1 million shares at an average S$0.1949 each, bringing cumulative purchases to 7.399 million shares, or 0.21% of the share base.
This is still small but the more interesting thing is what the repeated purchases might signify. The maths makes buybacks compelling.
At 30 June 2026, YZJ Financial had S$1.852 billion of net assets, equivalent to S$0.53 a share, while carrying zero borrowings. Cash and cash equivalents stood at a hefty S$575.4 million.
Compare that 53-cent NAV with the latest buyback price of 19.49 cents.
|
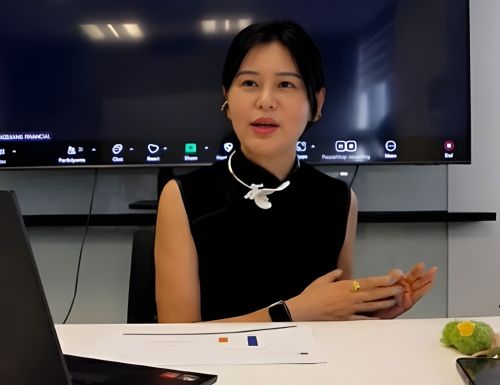 YZJ Financial Executive Chairman Liu Hua at FY25 results briefing: She was previously CFO of YZJ Shipbuilding, before moving on to be Deputy CEO and CFO of YZJ Financial.
| Attractive discount |
YZJ Financial is effectively buying its own shares at only about 0.37 times book value, or a 63% discount to NAV.
That's attractive.
|
Date (2026) |
Shares bought |
Price/share |
Total ($'000) |
|
3 Sep |
2,000,000 |
S$0.1977 |
$395.79 |
|
10 Sep |
1,000,000 |
S$0.2000 |
$200.19 |
|
11 Sep |
1,000,000 |
S$0.1990 |
$199.20 |
|
21 Sep |
398,700 |
S$0.1990 |
$79.42 |
|
23 Sep |
1,000,000 |
S$0.1990 |
$199.20 |
|
24 Sep |
1,000,000 |
S$0.1950 |
$195.19 |
|
25 Sep |
1,000,000 |
S$0.1949 |
$195.09 |
|
Total |
7,398,700 |
~S$0.1979 weighted average |
$1.46m |
Its S$575 million cash pile alone works out to roughly 16.5 cents a share. In other words, at around 19–20 cents, the market is assigning only a modest value to everything else YZJ Financial owns.
At 19.5 cents, market capitalisation is roughly S$677 million, while June cash alone was S$575 million.
So the market cap exceeds the cash pile by only about S$100 million.
And there is plenty else. Total AUM (assets under management) was S$1.82 billion at end-June.
But there is some bad baggage: old China loans that are non-performing and may not be fully repaid.
But the company has already made large provisions for them -- so much of the bad news has already found its way into the accounts.
Of the S$667.2 million in non-performing loans, it has already recognised S$439.2 million of provisions for possible losses.
That leaves only S$228 million still carried on its books, equivalent to about 12.5% of total AUM.
| Management had been cautious about buybacks |
At its March 2026 results briefing, Executive Chairman Liu Hua said the company intended to maintain about 20% of its portfolio in cash, partly to support dividends and potential share buybacks.
She also reiterated its 40% dividend payout policy.
Interestingly, the buybacks come after management said at April's AGM that a “calibrated share buyback programme” that did not materially affect cash flow would be considered.
Management acknowledged the merits of buybacks but argued that capital allocation had to balance share repurchases, dividends and investment opportunities.
It said using a "disproportionate amount of cash" for buybacks could leave the portfolio more concentrated and would not solve the longer-term need to grow earnings and diversify away from China exposures.
In other words, management's priority was to build the business first.
By June, approximately 70% of its RMB1 billion investment programme had been deployed, while the asset mix moved from 49% debt / 14% equity / 37% cash at end-2025 to 44% / 24% / 32% respectively.
Singapore AUM more than doubled from S$48.3 million to S$121.2 million.
So far, Yangzijiang Financial has spent only about S$1.46 million buying back shares, which is loose change as it retained S$575 million of cash and no debt as at June. The 7.4 million shares bought so far won't materially move EPS or NAV per share. They represent only about 0.2% of the share base. If purchases eventually reach 1%, 3% or 5% of the share base while the stock continues trading at a massive discount to its 53-cent NAV, investors will recognise that the buybacks are more than a gesture of confidence. |
 For earlier story, see: YZJ FINANCIAL Has Zero Debt and $640 M Cash Hoard. Stock Has Fallen To 55% NTA |


