|
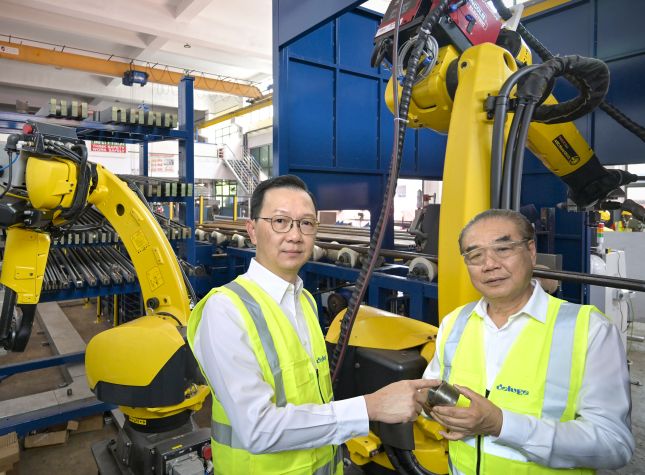
Deluge Corporation may not be a household name, but its project references certainly are: Marina Bay Sands, the North-South Corridor, MRT lines and data centres in Johor. |
| Big projects, substantial backlog |
Deluge is one of eight contractors holding the highest BCA grading for fire-protection work, allowing it to tender for public-sector projects without a value ceiling.
Arguably, that experience and technical requirements further narrow the field for complex jobs.
Its advantages include established supplier relationships and prefabrication.
The prospectus puts its outstanding order book at S$433.04 million on 16 September 2026, compared with S$410.81 million at March-end. That represents substantial secured work, which is expected to be mainly fulfilled over the next four financial years.
Group FY2026 pro forma revenue was S$116.6 million, down from S$139.8 million.
Profit attributable to shareholders fell to S$11.2 million from S$15.1 million.
Management says the decline needs some context: FY2025 was unusually strong as several major projects reached peak execution, while FY2026 represented a normalisation in activity.
| The more profitable second act |
Deluge’s Lifecycle Services business handles maintenance, repairs, upgrades and alterations to existing systems.
In FY2026, it contributed approximately S$35 million, or 30% of group revenue.
More strikingly, its 53.1% gross margin was over twice Integrated Projects’ 24.8%, allowing services to generate roughly half the group’s gross profit.
In the table below, the striking takeaway is that Lifecycle Services generated almost half of Deluge's FY2026 gross profit despite contributing only 30% of revenue:
|
Lifecycle Services |
FY25 |
FY26 |
|
Share of group revenue |
20.2% |
30.0% |
|
Estimated segment revenue |
S$28.2m |
S$35.0m |
|
Gross margin |
44.4% |
53.1% |
|
Estimated segment gross profit |
S$12.5m |
S$18.6m |
|
Share of group gross profit |
29.5% |
48.0% |
That is where Deluge’s business model becomes more interesting. Winning an installation job potentially creates a customer relationship lasting far beyond construction: maintenance, inspections, repairs, upgrades and alterations can continue for years.
| Data centre and T5 opportunities |
Malaysia offers another growth avenue. Data centres contributed about one-quarter of Integrated Projects revenue.
Unlike large Singapore infrastructure jobs that may take years to complete, data-centre blocks can be executed in months.
According to The Edge, Deluge says it has already completed around 10 to 12 blocks with DayOne, has received its first contract from Sunway Construction, and is also talking to Gamuda.
Typical contracts are said to be worth around RM30 million to RM50 million per block, while another 12 data-centre blocks have recently been approved in Johor.
If awards continue, this could become a meaningful contributor to revenue.
Then there is the wild card: Changi Airport Terminal 5.
Management says the fire-protection contract could be worth around S$370 million to S$380 million. Winning it would be transformational — potentially adding an amount close to Deluge's entire existing order book.
The IPO price at 60 cents implies a post-listing market value of S$87 million. That is 7.8 times earnings pro-forma FY2026 earnings. Transport and infrastructure represented 86.5% of the March order book. Not all Lifecycle Services income (and its unusually strong 53% margin) are contractually recurring: renovations and alterations are less predictable than routine maintenance. That is just one attraction of a capable specialist with substantial secured work and valuable after-sales relationships. |