|
Excerpts from UOB Kay Hian report
Analysts: John Cheong & Tang Kai Jie
Meeting Highlights: Strong Brand Equity Supports Inflation Resilience; Russian Risks Warrant Differentiated Assessment
• FEH’s strong brand equity and extensive distribution network provide an operational hedge against prolonged inflation, supporting demand resilience, pricing power and potential market-share gains.
• FEH’s Russian operations remain unaffected by recent measures against Nestlé. |
|||||
| Analysis |
• Brand equity and distribution infrastructure support inflation resilience and Russia risk requires a differentiated assessment. Our recent Kuala Lumpur non-deal roadshow highlighted investor concerns over prolonged input-cost inflation amid the Middle East conflict and Russia’s intervention in Nestlé’s local business.
Food Empire Holdings’ (FEH) strong brand equity, extensive distribution network and experience operating in volatile markets provide an operational hedge against inflation and could support further market-share gains.
While Russia remains a key geopolitical risk requiring continued monitoring, Nestlé’s situation should not be directly extrapolated to FEH or justify excluding Russian earnings from its base-case valuation.
• Brand equity and robust network provide an operational hedge against inflation. Investors raised concerns over prolonged inflation, particularly rising energy, sugar, packaging and logistics costs, alongside climaterelated risks to coffee supply.
FEH’s established brands and extensive distribution network support pricing power, product availability and customer retention.
Its experience in managing commodity inflation and supply-chain disruptions also allows for price adjustments, product-mix optimisation and supply flexibility. 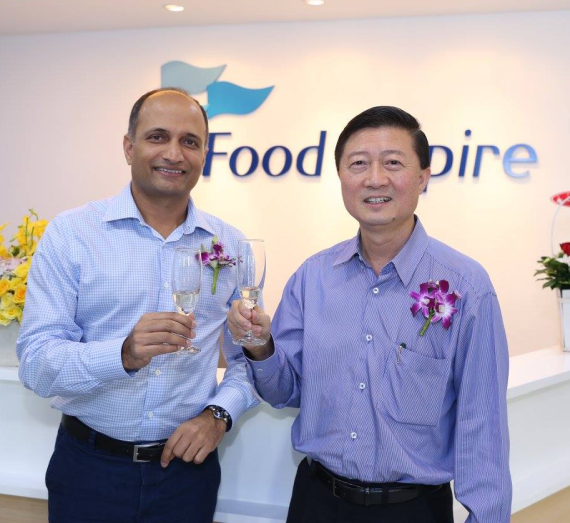 CEO Sudeep Nair with Executive Chairman Tan Wang Cheow
• Affordable products reinforce demand resilience. FEH’s coffee products occupy an affordable, everyday consumption category.
Consumers facing tighter household budgets may continue purchasing packaged coffee while reducing spending on more expensive discretionary occasions. Brand familiarity, convenient availability and accessible pricing support this demand.
In Vietnam, Café Phố’s established consumer franchise and distribution reach provide a strong platform for managing pricing while preserving purchase frequency.
Affordability remains essential, and price increases have been calibrated carefully.
• Industry cost pressure could strengthen FEH’s competitive position. Prolonged inflation could benefit established operators as smaller competitors face difficulties managing inventories, promotions and rising operating costs.
FEH’s strong brand equity and distribution infrastructure position it to maintain market presence and potentially gain shelf space and market share. Distributors and retailers may also favour trusted brands with reliable product turnover.
• Geographic exposure offers a potential additional buffer. FEH’s exposure to energy-producing economies, particularly Russia and Kazakhstan, could partially offset higher operating costs elsewhere.
Elevated energy prices may support export revenues, economic activity and consumer spending in these markets, benefitting consumers’ demand.
| On extrapolation from Nestle .... |
• Linear extrapolation from Nestlé to FEH is analytically unsound. Investors raised concerns over whether Russia’s intervention in Nestlé’s local business could pose similar risks to FEH. However, FEH’s Russian operations remain normal, with no indication of similar intervention reported during the roadshow.
While the Nestlé development highlights geopolitical risks, differences in ownership, operating arrangements and local relationships warrant a company-specific assessment.
Singapore’s targeted sanctions and continued diplomatic engagement with Russia also provide relevant context. Although intervention risks remain, Nestlé’s situation should not be directly extrapolated to FEH.
• Excluding Russian earnings belongs in an extreme downside scenario. Removing FEH’s entire Russian earnings contribution would assume a complete loss of the business’ economic benefits, representing an extreme stress case rather than a base-case assumption.
While such a scenario helps assess downside risks, FEH’s ongoing operations and earnings contribution should continue to be reflected in valuation, with appropriate adjustments for geopolitical risks.
Key considerations include operational continuity, cash accessibility, currency exposure and potential government intervention.
Although risks remain, excluding Russian earnings entirely without company-specific evidence would be premature.
• Maintain BUY with an unchanged PE-based target price of S$3.49, pegged to 25x 2026F PE or 2SD above the long-term average.  John Cheong, analyst The stock trades at only 12.2x 2027F PE, a 39% discount to the peer average of 20x. |
 See also: This Multi-Continent Business Delivers Record Revenue, Record Profit, Record Dividends, Record Stock Price |


