|
Excerpts from UOB Kay Hian report
Analysts: John Cheong & Shaina Mahtani
Positive Highlights From Meeting Reinforce Growth Outlook
• Key takeaways from our recent meeting with management suggest that CSE’s outlook remains positive, with more DC contract wins expected by end-26 as well as strong potential for more contracts from the second hyperscaler.
|
|||||
Analysis
| Key highlights from management meeting |
CSE Global (CSE) highlighted that existing data centre (DC) contracts remain intact, with continued opportunities for new project wins. 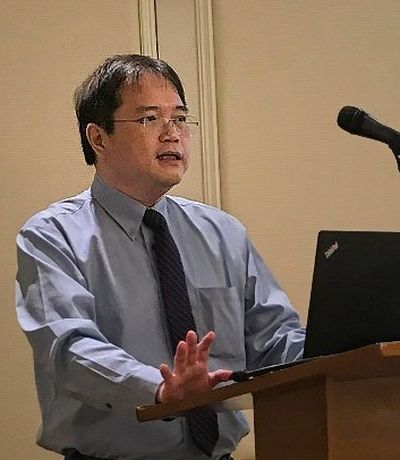 Lim Boon Kheng, MD of CSE Global.Management remains optimistic about continued order momentum, with further contract wins expected in 4Q26 as major customers finalise their projects for the following year.
CSE's DC exposure to US government end-users provides some insulation against funding risks, given their relatively low credit risk and long-term project commitments.
CSE has also commenced work with a second hyperscaler, presenting further growth opportunities as it expands its presence in the US DC market.
S$254.8m in new US electrification contract wins. CSE has secured three major US electrification contracts worth a combined S$254.8m in Aug and Sep 26, comprising:
a) a S$64.3m contract accounted in Aug 26 for the design and manufacture of power distribution centres (PDC), together with the integration of electrical and control systems, for the Cheyenne Power Hub project in the US, and
b) two additional contracts worth S$190.5m in Sep 26 for works on the Calcasieu Pass 2 (CP2) LNG project in Louisiana and a follow-on order for the Cheyenne Power Hub project.
These contracts will be executed progressively between 2026 and 2028.
| Strong contract wins support orderbook and revenue visibility. |
The S$254.8m in new contract wins is equivalent to approximately 41% of CSE's S$620m orderbook as at end-1H26, reflecting sustained order momentum and strong demand for its electrification solutions.
Management expects further order wins in 4Q26, as major US customers typically finalise their project requirements for the following year during this period.
With project deliveries extending into 2028, we expect these new contracts to provide greater medium-term revenue visibility and support CSE's growth prospects.
Capacity expansion to accommodate demand. CSE plans to expand production capacity further in 2027 to accommodate growing demand from hyperscalers, favouring leased facilities to preserve capital.
Meanwhile, communications should continue to provide stable contributions, while automation is expected to recover as costs related to the wind-down of water and wastewater projects normalise.
Near-term outlook remains resilient despite AI funding concerns. The recent sell-off in AI-related stocks has raised concerns over rising financing costs, potential DC oversupply and slower hyperscaler capital expenditure, which could weigh on future demand for CSE's electrification solutions.
We believe CSE's existing orderbook provides a degree of insulation from nearterm market uncertainties, supported by its focus on established hyperscalers and end-customers with long-term commitments.
While a prolonged slowdown in DC investments remains a risk to future order intake, we expect CSE's near-term operating momentum to remain intact.
Operating efficiency expected to improve in 2H26. CSE's operating performance is expected to strengthen in 2H26 as the temporary cost pressures experienced in 1H26 gradually ease.
Start-up costs at the Champion Park facility should normalise as operations ramp up towards steady-state, while the completion of water/wastewater project wind-downs should reduce additional cost pressures.
Alongside improving project execution and continued demand for electrification solutions, these developments should support stronger operating margins and profitability in 2H26.
|
S$m |
FY26F |
FY27F |
FY28F |
|
Revenue |
1,125.7 |
1,226.9 |
1,299.8 |
|
Net profit |
39.9 |
44.9 |
47.9 |
|
Net margin |
3.5% |
3.7% |
3.7% |
Electrification remains the key growth driver. CSE's electrification segment continues to anchor its growth outlook, supported by increasing investments in US DC and LNG infrastructure.
The segment recorded a robust revenue growth of 64% yoy in 1H26, significantly outpacing the communications and automation segments.
CSE is focusing on financially strong hyperscalers, with AWS switchboards and electrical distribution centres (EDC) for a second hyperscaler underpinning growth.
We expect the electrification segment to remain the group's main earnings growth driver, supported by sustained infrastructure demand, recent contract wins and the ramp-up of its Champion Park facility.
Maintain BUY with an unchanged target price of S$1.79, based on an unchanged 29x 2027F PE (+1.5 SD to mean). |
 See also: CSE GLOBAL: UBS Initiates Coverage, Sees an AI Power Story Beyond Amazon |


