UOB Kay Hian says the sell-down looks “overdone” and has created buying opportunities.
|
Excerpts from UOB Kay Hian report
Analysts: Tang Kai Jie & John Cheong
Strategy – SMID Cap Corporate Day
• Pan-United (PAN), Hong Leong Asia (HLA) and Huationg Global (HUAGL) participated in the SMID Cap Corporate Day on 21 Oct 26. |
| Key Takeaways |
• PAN: As of Aug 26, ready mixed concrete (RMC) volume of 10.9m m³ points to above 16m m³ for FY26, ahead of BCA's 15m-16m m³ forecast.
Capacity is up 20-30% compared with 2024; more Changi T5 superstructure orders are expected, and variable pricing helps pass through elevated diesel costs.
PAN’s 40% market share continues to emphasise its competitive edge in the RMC market in Singapore.
Maintain BUY with a target price of S$1.88, pegged to 17x 2027F PE.
The stock currently trades at 14.6x 2027F PE.
• HLA: Yuchai shipped around 2,000 AI genset engines in 1H26, with 2026 capacity of around 5,000 units at higher margins.
Exports are growing 30- 50% yoy, while HLA's effective Yuchai stake has risen to around 48% and the Hong Kong IPO of a Yuchai unit is under China Securities Regulatory Commission (CSRC) review.
Maintain BUY with a SOTP-based target price of S$4.70. The stock trades at 11.4x 2027F PE.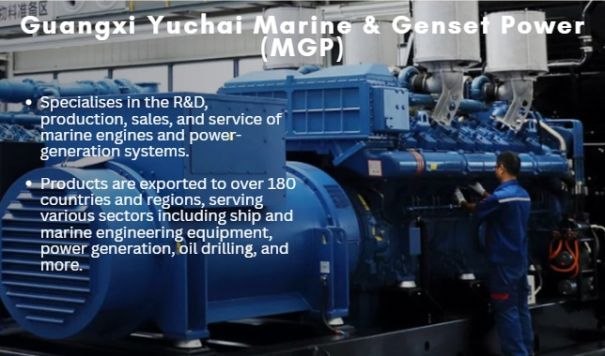
• HUAGL: Orderbook of S$556m rises to above S$600m including variation orders (VO), with a tender book of around S$600m up to 1Q27.
The government’s fuel reimbursement is expected around Dec 26, and new contracts have priced in higher fuel costs, supporting cost and margin recovery.
Maintain BUY with a target price of S$0.88, pegged to 10x 2026F PE.
The stock trades at 5.7x 2026F PE.
| Our View |
• Investor interest: Investors were focused on the sustainability of Singapore's construction upcycle, whether the cycle has peaked, the impact of higher diesel costs and the ability to pass them through, as well as orderbook visibility.
For HLA, discussions centred on the AI genset opportunity and value unlocking at Yuchai.
• Our comments: Management teams were broadly upbeat, citing a robust public infrastructure pipeline (Changi T5, MRT lines, HDB, Tengah Air Base) that should keep construction demand elevated over the next 2-3 years.
Easing fuel costs should support margin recovery into 2027.
• Positive on all three: HLA offers strong upside on powertrain growth and value unlocking, HUAGL’s deep valuation discount looks overdone given its margin recovery path, and PAN remains a quality proxy to the construction upcycle with steady dividends.
|
 See also: This Contractor's Profit Has Exploded. Its Valuation Hasn't -- At Just 1.6x PE |


