|
October 2026 has seen Wee Hur Holdings make three key operational announcements.
|
| Keeping a major earner going |
On 27 October, Wee Hur announced that JTC had extended Tuas View’s land lease by two years and eight months, from 1 November 2026 to 30 June 2029.
The significance is its scale.
Tuas View’s 15,744 beds represent about 60% of the group’s 26,244 worker accommodation beds. Losing the right to operate such a large asset would have threatened a substantial part of its accommodation business.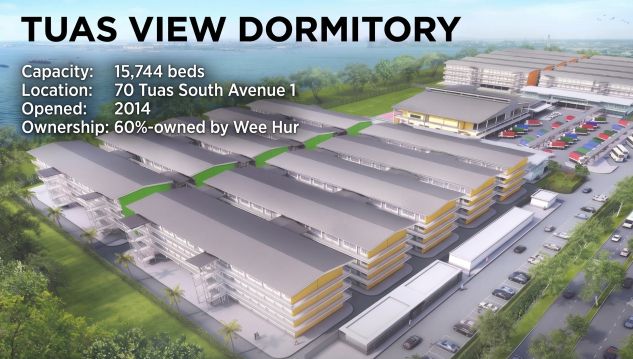
Tuas View averaged 92% occupancy in the first half of 2026, with stable rents.
Wee Hur says Tuas View already meets interim dormitory standards, allowing operations to continue without disruption to residents and their employers.
“The extension of Tuas View Dormitory reflects the trust built over more than a decade of operating one of Singapore’s largest workers’ dormitories. It gives us continued income visibility from an established asset and reinforces our workers’ dormitory business as a stable source of recurring income for the Group.”
– Goh Chengyu, CEO, Wee Hur Property
Meanwhile, the new 10,500-bed Pioneer Lodge is filling up.
Wee Hur says occupancy is expected to reach 97% on 1 Nov, compared with an average of 66% in 1H2026. More occupied beds should support its rental income.
The workers’ dormitory division generated S$63.3 million of revenue in 1H2026, up 50.7% from a year earlier.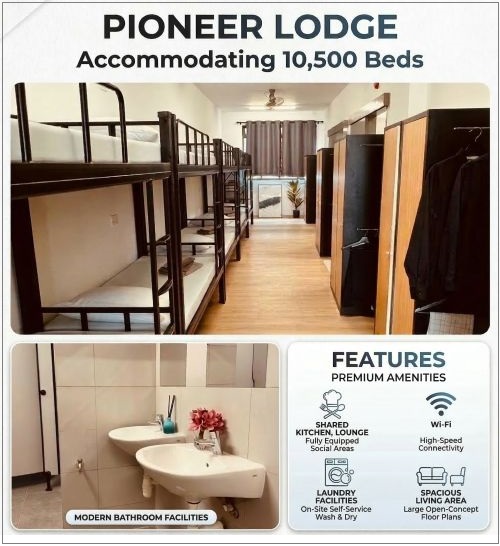
| NTU opens another door |
Announced on 16 October, the NTU award covers approximately 1,398 student beds, mainly for postgraduates. It will be Wee Hur’s first Y Suites property in Singapore, extending its student housing business beyond Australia and Hong Kong.
For perspective, Wee Hur’s UniLodge Park Central development in Brisbane has 1,578 beds. NTU would therefore rank among its largest individual student accommodation projects.
Wee Hur will design, build, finance, operate and maintain the development. This gives it an opportunity to apply its experience across the property cycle and earn accommodation income over time.
To help finance the project, Wee Hur expects to lend S$60 million to the project company, in which it owns 80%. That commitment represents approximately 9.4% of its latest audited net tangible assets, as measured at 31 December 2025.
The S$60 million is capital Wee Hur plans to provide to the venture. Neither the construction contract value nor the total development cost has been disclosed.
Construction is targeted for 3Q2027, with operations expected by the 2029/30 academic year. The definitive agreement is still being finalised, and the project is subject to approvals.
The proposed initial land lease is 20 years, with options for two further five-year terms.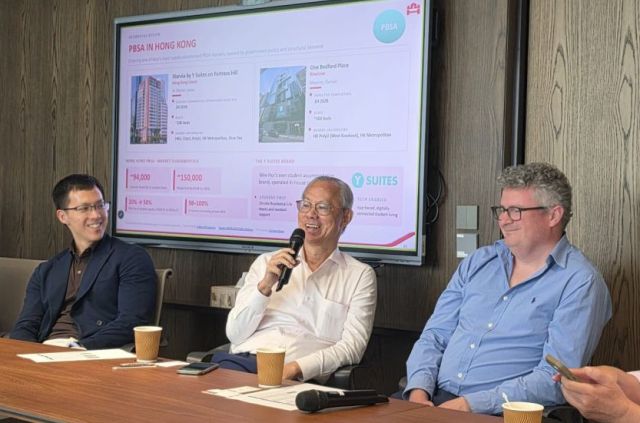 At 1HFY26 results briefing (L-R): CIO Goh Wee Ping, Executive Chairman Goh Yeow Lian, CEO Wee Hur (Australia) Scott Peter William. Photo: Company
The NTU news was followed by another one about Wee Hur securing an unconditional option for the proposed acquisition of a 2,744 sqm site at 35–51 Nicholson Street, Wollstonecraft, Sydney, with acqusition completion expected in 2H2027.
The site is earmarked for a 12-storey, 471-bed purpose-built student accommodation.
The three announcements complement one another: Tuas View preserves existing earning capacity while NTU and Sydney projects create potential new sources of income. The eventual contribution from the new student accommodation projects will depend on development costs, financing terms, rental rates and occupancy. Wee Hur is positioning itself for a larger, more diversified recurring-income business, with multiple avenues for growth across Singapore, Australia and Hong Kong. |
 See also: WEE HUR: Why Its Australian Land Could Become a Growth Engine |


